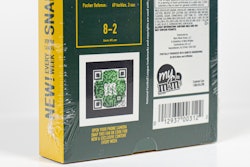
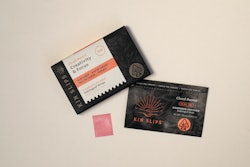
But if you squint your eyes enough to blur the notable exceptions, and take the market in aggregate, what swims into view can only be described as quickly increasing sophistication in cannabis packaging.
The first wave of states to decriminalize or outright legalize recreational cannabis, namely the contiguous Pacific states plus Nevada and Colorado, haven’t transitioned the marijuana plant into your typical, CPG-style, branded commodity without their share of setbacks. Previously existing (read black) markets persist, and over-licensing flooded the market with product and drove prices down. Save perhaps for Nevada, today those markets are drum-tight after the initial vacuum and rush to hang out a shingle. They remain extremely fragmented even within each state, characterized by a wide array of small brands with a few employees—each specializing in vape, edibles, pre-rolls, or flower, and each clinging to a narrow patch of market share. As it stands, there’s little foot-in-the-door share to be earned by newer cannabis brand interlopers, at least not until federal laws level the playing field.