Mars Snacking is redesigning its flexible packaging to comply with emerging regulations like EPR programs and the EU's PPWR by replacing multi-material laminates with mono-material films and advanced chemical coatings, requiring new expertise in material transparency, regulatory compliance, and supply chain data management.
- Mars is transitioning from multi-material laminates to mono-material films to meet EPR and PPWR compliance requirements.
- Chemistry and coatings now replace physical layers, requiring expertise in barrier coatings, additives, inks, and adhesives previously handled by lamination.
- Brands must now maintain complete transparency on all components, including thin layers of ink, coating, and adhesive, and file detailed compliance reports.
- EPR fee differences can range from 4 cents to 78 cents per pound based on material classification, making accurate data and supply chain transparency critical.
- Redesigns typically take longer than expected and require balancing food safety, performance, cost, recyclability, and carbon emissions simultaneously.
Mars Snacking’s brands, from Snickers and M&M’s to Pringles and Cheez-It, rely heavily on flexible film.
“The majority of our packaging is much smaller than a piece of paper, smaller than an envelope even,” said Laura Shimmin, associate director of global packaging R&D at the company this week.
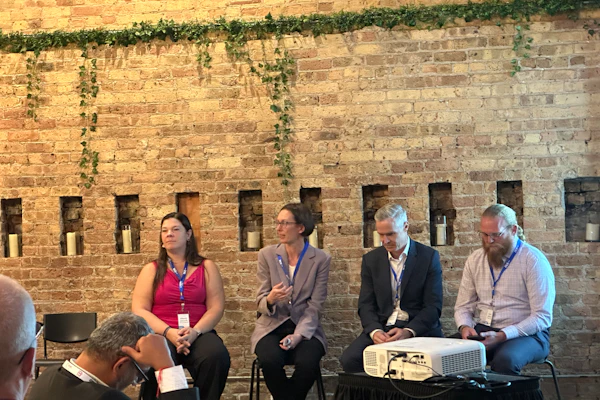
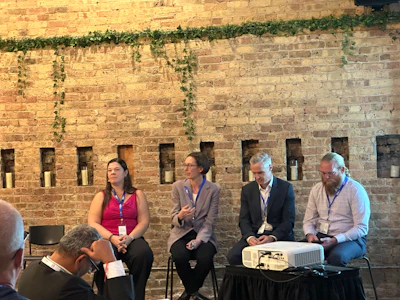
That format profile puts Mars squarely in the path of emerging packaging laws, from extended producer responsibility (EPR) programs in U.S. states to the EU’s Packaging and Packaging Waste Regulation (PPWR). Shimmin spoke on a panel at INX International’s Innovation Day, held during PACK EXPO International earlier this week in Chicago, alongside Stefan Laske, head of R&D for consumer flexibles at Mondi, Greg Stillman, director of the new materials and packaging vertical at innovation platform and investor Plug and Play, and Lowell Huffman, director of channel partnerships at EPR compliance firm rePurpose Global.
“Two or three years ago we were talking about our voluntary commitments. We were talking about either internal commitments or external commitments we had made because we wanted to,” Shimmin said. "Now that conversation has shifted to talking about what we must do in terms of redesign.” Brand owners such as Mars now file their own EPR reports, which makes the inks, adhesives, coatings, and additives in a structure their responsibility. Under PPWR, California’s SB 54 and SB 343, and AB 1200, a single fluorinated processing aid or incompatible coating can push a pack to a failing recyclability grade, over a PFAS limit, or into a higher fee category.
Chemistry fills the gap
“If I had a layer [of film] as part of my [packaging] system before and I’m physically taking that layer out, that layer wasn’t there for niceties. It had a performance attribute,” said Stillman.
As brands move from multi-material laminates to mono-material film or recyclable paper, that performance increasingly has to come from coatings, additives, inks, and adhesives. Startups working on barrier coatings are developing water-based dispersions, mineral and inorganic nanocoatings, and bio-based coatings meant to replace PE lamination, EVOH, PVDC, and metallization. Stillman called PFAS replacement a tougher target, because fluorinated chemistries deliver oil, grease, and water resistance all at once and set a high benchmark.
“Two or three years ago we were talking about our voluntary commitments. We were talking about either internal commitments or external commitments we had made because we wanted to,” Shimmin said. "Now that conversation has shifted to talking about what we must do in terms of redesign.”
Plug and Play screens new packaging technologies against six criteria, which are regulatory fit, performance parity, recyclability evidence, scalability on existing flexo, gravure, and coating lines, total cost including eco-modulated EPR fees, and continuous compliance data. A technology that fails any one of them won’t reach the shelf.
“There is no more sustainability premium that I think buyers are willing to shoulder,” Stillman said.
What the spec now covers
The value chain behind a Mars flexible pack runs through several companies. Mondi produces the substrate and converts it into printed rollstock of film or flexible paper, using inks and barrier chemistries from suppliers such as INX International. Mars specifies the combination of substrate and chemistry it will qualify and run on its own lines.
“For us it’s about food safety, number one. Performance and cost are kind of those non-negotiables,” Shimmin said. “But now I think in addition to asking for all of those things, we’re starting to talk about new materials. We’re talking about mono-materials, we’re talking about fiber materials, we’re talking about recycled. It has to be certified, it has to be traceable.”
“All of these individual components, we need to know everything about them,” she added. “We need to know how much there is. We need to know what’s in them, what’s not in them.”
That includes the thin layers of ink, coating, adhesive, and additive in a structure. “We relied on the expertise in our supply chain to kind of make the recommendation and bring it forward,” Shimmin said. “Now we’re a responsible entity a lot of the time. We’re the ones that have to file the reports. We’re the ones that have to submit and say that this has met all the requirements, and I believe it to be true.”
“It’s really getting into the details of what is this test result? What does it mean? Why are we seeing these borderline results?” she said. “In my mind, in a positive way, but maybe a little bit of an uncomfortable way. It’s like new muscle.” PPWR has applied since Aug. 12, 2026, and it works as a product rule rather than a fee, so packaging that doesn’t comply can’t be sold in the EU. Recyclability grades A–C become mandatory in 2030. In California, SB 54 requires all covered packaging to be recyclable or compostable by 2032, and eco-modulated producer fees through Circular Action Alliance start in 2027, so redesign has become a requirement for brand owners like Mars rather than a voluntary pledge.
The converter’s view
“For us it’s about food safety, number one. Performance and cost are kind of those non-negotiables,” Shimmin said. “But now I think in addition to asking for all of those things, we’re starting to talk about new materials. We’re talking about mono-materials, we’re talking about fiber materials, we’re talking about recycled. It has to be certified, it has to be traceable.”
Replacing a multilayer structure with a mono-material one while holding every legacy requirement fixed usually means higher cost at first, said Laske. Incumbent structures have had decades of optimization, while new ones are only starting down the learning curve, and he expects cost and efficiency to improve as they mature. He added that brand owners routinely underestimate how long a redesign takes, and that waiting until a compliance deadline nears is risky.
Laske suggested that brand owners and converters revisit some long-standing specifications, such as an 18-month shelf life or certain abuse tests like 5-m drop tests. Some of those requirements exist because legacy materials could meet them, he said, not necessarily because the product needs them.
For fiber-based substrates, compostability is a newer request, and Laske said few solutions on the market deliver it alongside barrier. On film, he sees growing demand for coatings that combine two properties, such as barrier and adhesion, in a single layer. Plug and Play judges a new packaging technology’s cost only after counting eco-modulated EPR fees and avoided redesigns. It also wants recyclability results from a recognized body such as APR, RecyClass, or CEFLEX by 2028. A technology that misses any one of the six criteria won’t reach the market, no matter how strong its chemistry.Slide presented by Greg Stillman, Plug and Play
Weighing the trade-offs
Laske suggested that brand owners and converters revisit some long-standing specifications, such as an 18-month shelf life or certain abuse tests like 5-m drop tests. Some of those requirements exist because legacy materials could meet them, he said, not necessarily because the product needs them.
Every redesign carries trade-offs. Laske said the industry has seen packs designed for full recyclability that ended up with higher carbon emissions, and that moving from plastic to paper can raise CO2 emissions as well. For Mars, packaging changes that would create food waste are generally off the table, since lost product usually carries a bigger impact than the package.
Small formats raise a second end-of-life question, Shimmin said. Mars has to design for the recycling system a pack is intended for and also consider what happens if it ends up in the environment instead. Mars has also tried to align with fellow brand owners as well as its supply chain, so companies move toward the same targets rather than each solving for something different.
“End of life for us is front and center about the problem that we’re trying to solve,” Shimmin said. “So that kind of gives me some hope that maybe we are actually moving in the right direction and not creating a lot of those unintended consequences.” In Plug and Play’s model, brand owners set the spec and share SKU-level data for EPR fee calculations, and converters validate structures on real lines at real speeds. Chemistry suppliers such as INX formulate the inks, coatings, and dispersions that let a recyclable structure perform. Startups add barrier, PFAS-free, and recycling-aid technologies, drawn from the roughly 100,000 that Plug and Play tracks.Slide presented by Greg Stillman, Plug and Play
Fees put a price on the decision
EPR schemes are built to drive change through eco-modulation, the bonuses and maluses applied to producer fees, said Huffman. Brands need a defensible chain of custody to claim those incentives. Across the more than 1,800 EPR reports rePurpose Global has filed for brands, Huffman said, last-minute reporting is common, and because companies are compiling hundreds of thousands of data points for the first time, small errors can inflate fees dramatically.
Even minor components can change how a package is classified and reported. Huffman cited the gap between a fee of 4 cents/lb and 78 cents/lb for a material, multiplied across millions of units. California’s SB 54 source-reduction target also counts the number of plastic components, he said, not only plastic weight. That puts the burden on suppliers to deliver granular material data as a routine part of what they ship.
Shimmin said more suppliers now want to talk directly with brand owners about requirements. The exchange can run the other way as well, she said, with brand owners helping explain to smaller suppliers deeper in the chain why the data is needed and how it will be used.
For Shimmin, the part of the value chain that could do the most to speed packaging innovation is waste management and recycling infrastructure. “I think there’s a lot of opportunity to kind of uniformly design towards one set of infrastructure expectations and requirements that would really influence everything else that we do,” she said.